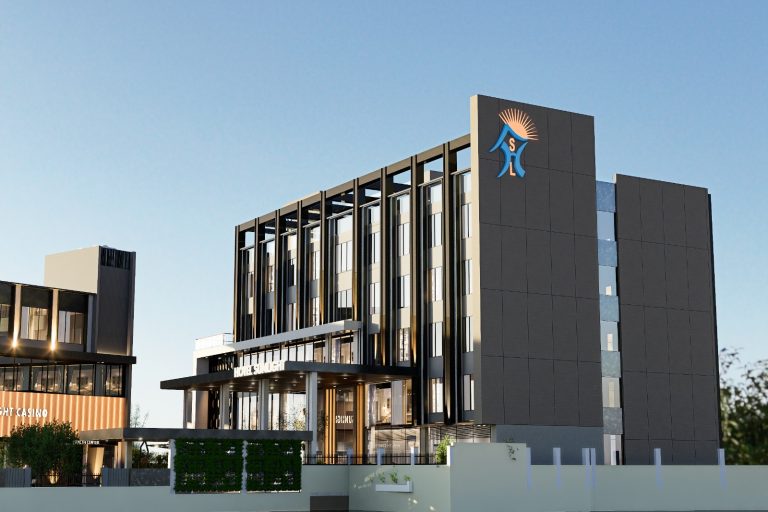
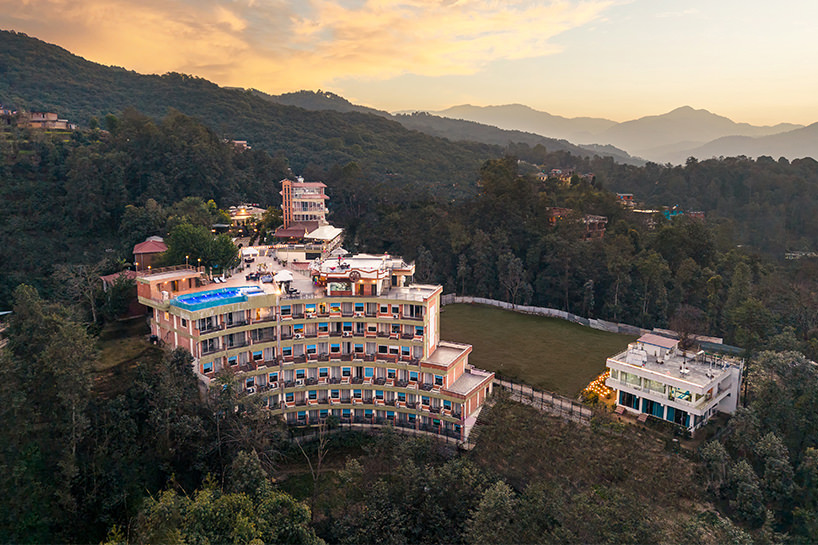
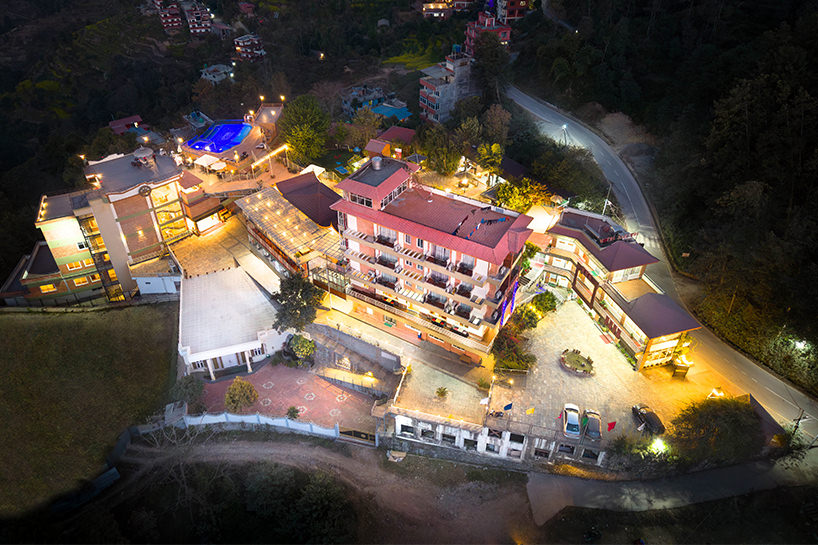
Hotel Sarathi Limited (HSL), which operates a four-star hotel in Dhulikhel, Kavrepalanchowk, has received an upgraded long-term bank facility rating of ‘CARE-NP BB-’ from CARE Ratings Nepal Limited (CRNL), reflecting an improvement in its financial profile, operating performance and debt protection metrics. CRNL has revised the rating assigned to HSL’s long-term bank facilities to ‘CARE-NP BB-’ from ‘CARE-NP B’ and reaffirmed its short-term bank facilities rating at ‘CARE-NP A4’.
The ratings have also been removed from the Issuer Not Cooperating Category after the company provided the requisite information to the rating agency. In addition, CRNL has assigned an issuer rating of ‘CARE-NP BB- (Is)’ to Hotel Sarathi Limited. According to CARE Ratings Nepal, issuers with this rating are considered to have a moderate risk of default regarding the timely servicing of financial obligations in Nepal. The company has total rated bank facilities of Rs. 600 million, comprising Rs. 590 million in long-term bank facilities and Rs. 10 million in short-term bank facilities.
Financial Performance Improves in FY26
The rating upgrade has been primarily driven by Hotel Sarathi’s improved financial profile in FY26, including stable operating performance, stronger cash accruals, and an improvement in its capital structure and debt protection metrics. According to CARE Ratings Nepal, the company reported total operating income (TOI) of Rs. 180 million in FY26, which remained largely stable compared with the previous year despite a significant increase in its room inventory. The company expanded its operational capacity from 20 rooms to 74 rooms by mid-January 2025, meaning FY26 represented the first full financial year of operations with the enlarged room inventory.
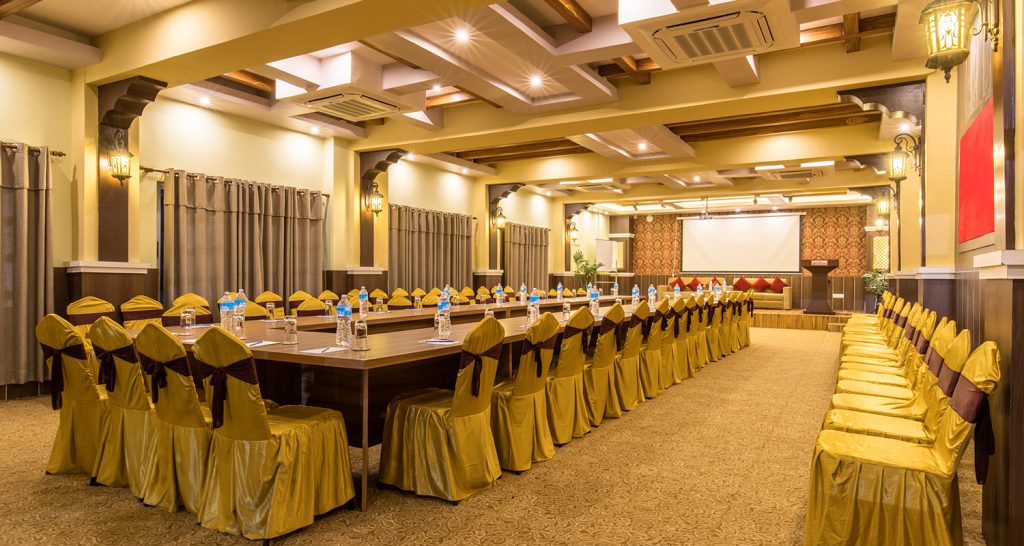
Despite the substantial increase in capacity, the company maintained a stable operating performance. Its occupancy rate stood at approximately 51% in FY26, similar to FY25, while occupancy had stood at around 46% in FY24. However, the average room rate moderated during FY26, limiting the overall growth in room revenue despite the higher number of available rooms. The company also achieved improved revenue diversification during the year, with food and beverage income accounting for 49.3% of total revenue in FY26, compared with 46.0% in FY25. The increased contribution from food and beverage operations helped reduce the company’s dependence on room revenue.
Cash Accruals Rise to Rs. 62 Million
Hotel Sarathi’s profitability and cash generation also improved during FY26. The company maintained its PBILDT margin at around 56%, supported by operating efficiencies and a relatively stable cost structure. As a result, gross cash accruals (GCA) increased to Rs. 62 million in FY26 from Rs. 52 million in FY25, strengthening the company’s ability to service its financial obligations.
CARE Ratings, however, noted that the company’s ability to improve occupancy and average room rates on a sustained basis will remain important for further growth in revenue and profitability. The successful absorption of the expanded room capacity and the sustainability of the resulting financial benefits will therefore remain key areas of monitoring.
Capital Structure and Debt Protection Strengthen
Hotel Sarathi’s capital structure improved during FY26, supported primarily by an increase in tangible net worth following equity infusion. The company’s overall gearing ratio improved to 1.13 times at the end of FY26 from 1.78 times in FY25, indicating a reduction in financial leverage.
Similarly, the company’s interest coverage ratio improved to 2.55 times in FY26 from 2.03 times in FY25, reflecting stronger capacity to meet interest obligations from operating earnings. However, total debt to gross cash accruals remained relatively high at 8.27 times at the end of FY26. CARE Ratings has therefore identified the company’s ability to sustain the improvement in its debt coverage indicators as a key monitorable factor going forward.
Expansion Brings Operational Stabilisation Risk
Although Hotel Sarathi has been operating for several years, CARE Ratings highlighted that the company has a limited track record at its expanded scale. HSL began operations with 20 rooms in June 2019 and gradually expanded its operational inventory to 74 rooms by mid-January 2025. Consequently, FY26 was the first full year in which the company operated with its expanded capacity.
Occupancy increased from around 46% in FY24 to approximately 51% in FY25 and remained at about 51% in FY26. While the stable occupancy performance is viewed positively, CARE Ratings noted that the company has yet to demonstrate sustained operational stabilisation at the enlarged capacity. The ability to increase occupancy and convert the additional room inventory into sustained growth in revenue and profitability will therefore remain a critical factor influencing the company’s future financial performance and credit profile.
Single-Property Concentration Remains a Concern
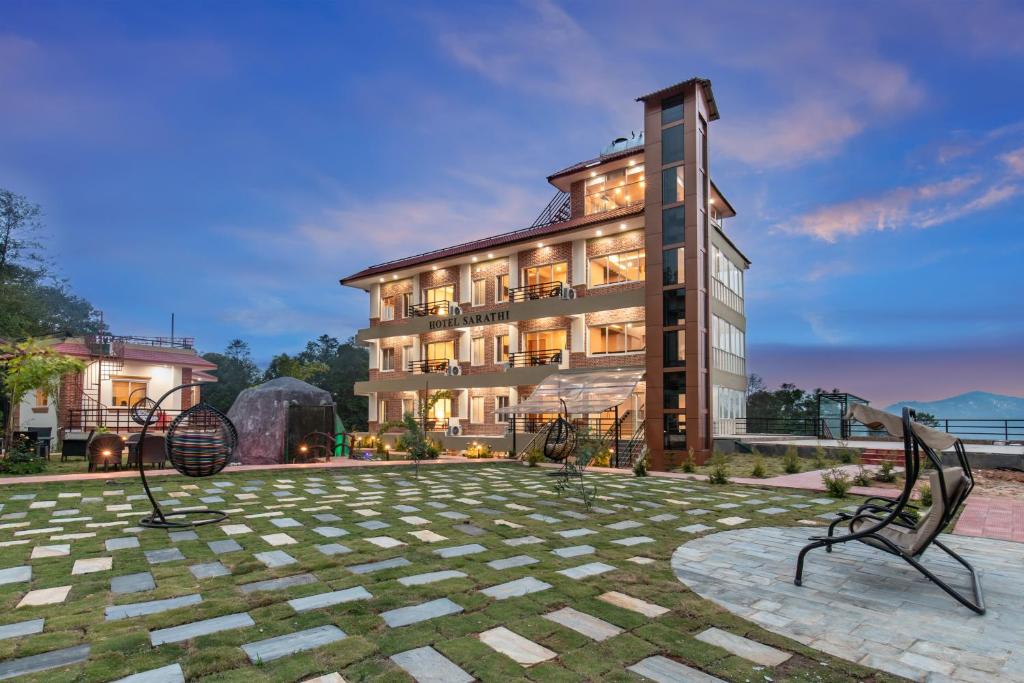
The rating continues to be constrained by Hotel Sarathi’s revenue and geographical concentration. The company operates a single hotel property in Dhulikhel, Kavrepalanchowk, exposing it to risks associated with dependence on one property and one geographic market. CARE Ratings noted that the absence of diversified operations across multiple regions or property types could affect the company’s ability to maintain stable cash flows during periods of reduced visitor arrivals or localized economic downturns.
As a hotel operating in the hospitality sector, Hotel Sarathi Limited (HSL)’s revenue and profitability are also exposed to the growth dynamics of the industry and regional tourism conditions. Any prolonged decline in tourist inflows or weaker domestic demand could put pressure on occupancy, room rates and cash generation.
Hospitality Sector Faces Cyclicality and Competition
CARE Ratings has also highlighted the cyclical nature and intense competition within Nepal’s hospitality industry. The country’s hotel sector remains fragmented, with a large number of organised and unorganised operators across different destinations. Hotel occupancy and revenues are influenced by broader domestic and international economic conditions, changes in tourist arrivals, consumer spending and travel trends.
For Hotel Sarathi, the concentration of operations in Dhulikhel further increases exposure to regional tourism dynamics. The company’s ability to maintain competitiveness, attract visitors and improve its occupancy and average room rate will therefore remain important to its long-term financial performance.
Floating Interest Rates Pose Financial Risk
The company is also exposed to fluctuations in interest rates because its borrowing costs are linked to floating interest rates. Hotel Sarathi Limited (HSL)’s interest rates are based on a floating-rate structure in which a premium is added to the monthly base rate of banks and financial institutions. Changes in liquidity conditions within Nepal’s banking system can therefore lead to changes in base rates and, consequently, the company’s interest expenses.
CARE Ratings noted that higher-than-anticipated interest rates could squeeze the company’s margins. However, the near-term outlook remains relatively favourable amid the declining trend in the base rates of Nepal’s banks and financial institutions observed over the past few years.
Experienced Promoters Support Operations
The Hotel Sarathi Limited (HSL) benefits from experienced promoters and a management team with significant exposure to the hospitality sector. Hotel Sarathi is led by Pralhad Pyakurel, Executive Chairman, who has more than two decades of experience in the hospitality industry. Other members of the board also possess experience across different industries, while Milan Shrestha, General Manager, has approximately three decades of experience in the hospitality sector and oversees the hotel’s overall operational management. The board is supported by an experienced team across various functions and departments. CARE Ratings considers the company to have a moderate operating track record of around four years.
Dhulikhel Location Provides Strategic Advantage
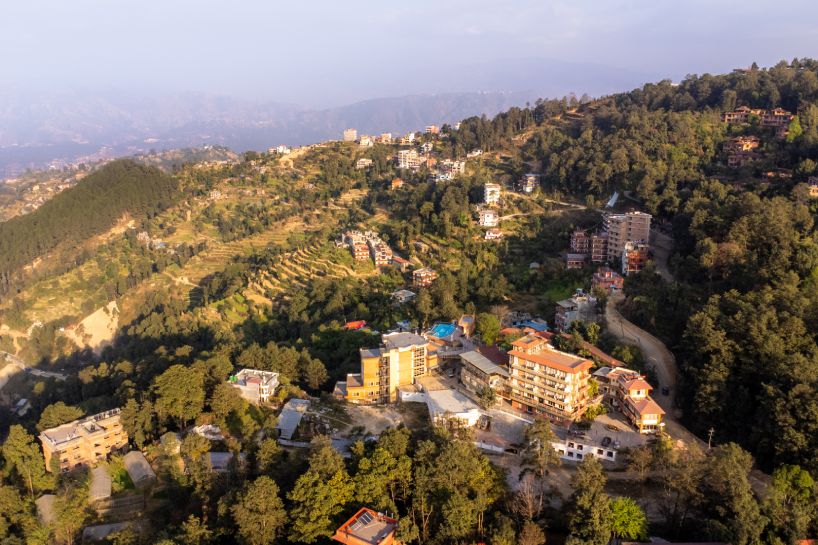
Hotel Sarathi’s location in Dhulikhel is considered one of its key strengths. The Hotel Sarathi Limited (HSL) is situated approximately 29 kilometres from Tribhuvan International Airport, providing relatively convenient access from Kathmandu. Dhulikhel is an important destination along the Kathmandu Valley Cultural Trekking Trail and serves as a stopover for travellers and mountain bikers travelling towards Tibet.
The destination is also known for panoramic Himalayan views, with visitors able to see more than 20 peaks, including Mt. Annapurna, Ganesh Himal and Langtang. Beyond its natural attractions, Dhulikhel has significant historical, religious and cultural value. The town is home to numerous Hindu temples, shrines and Buddhist stupas, enhancing its potential as a leisure, cultural and pilgrimage destination. The location therefore provides Hotel Sarathi with access to both domestic and international tourism demand, although the company remains exposed to the overall performance of the Dhulikhel tourism market.
Government Tourism Initiatives Support Industry Outlook
CARE Ratings has also identified continued government support for Nepal’s tourism industry as a positive factor for the company. Tourism remains one of the government’s priority sectors, with the FY27 budget placing emphasis on tourism-led economic growth through investments in heritage conservation, tourism infrastructure, trekking routes, destination development and aviation facilities.
The government has allocated approximately Rs. 7.34 billion for culture and tourism activities and Rs. 2.93 billion for civil aviation development in the FY27 budget. Key initiatives include expansion of the Greater Lumbini Development Programme, promotion of Janakpur as a wedding destination, development of the Great Himalayan Trail and regional tourism corridors, conservation of heritage sites and improvements to airport infrastructure.
The planned enhancement of Tribhuvan International Airport, Pokhara International Airport and Gautam Buddha International Airport, along with investments in tourism infrastructure, could support the broader growth of Nepal’s tourism sector and create a favourable operating environment for hospitality businesses.
Occupancy and Room Rates Key to Future Rating
Going forward, Hotel Sarathi’s ability to improve occupancy and average room rates will remain central to its financial performance and credit profile. CARE Ratings has identified sustained improvement in occupancy, ARR, income and profit margins as key rating sensitivities. Stronger operating cash flows, improved solvency and enhanced debt service coverage could further strengthen the company’s financial position.
At the same time, the rating will continue to be monitored against risks arising from the hotel’s single-property concentration, competition, tourism cyclicality, stabilisation of its expanded 74-room capacity and fluctuations in interest rates. The latest rating action reflects the improvement achieved by Hotel Sarathi in FY26, while its future credit profile will depend largely on whether the company can translate its expanded capacity and Dhulikhel location into sustained growth in occupancy, room rates, profitability and cash generation.