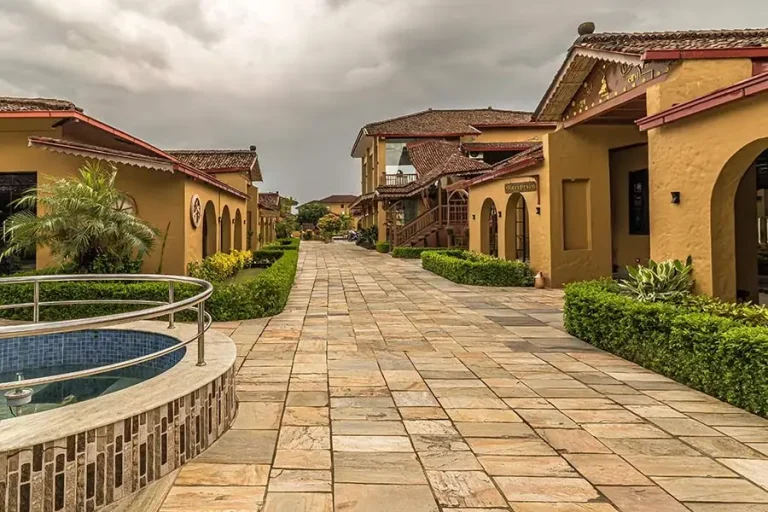
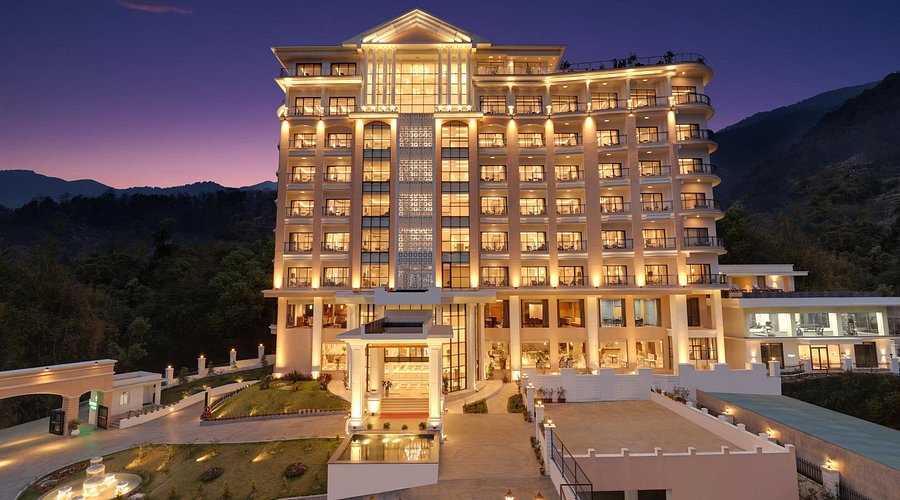
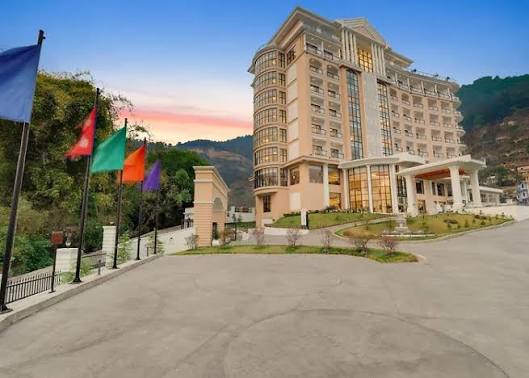
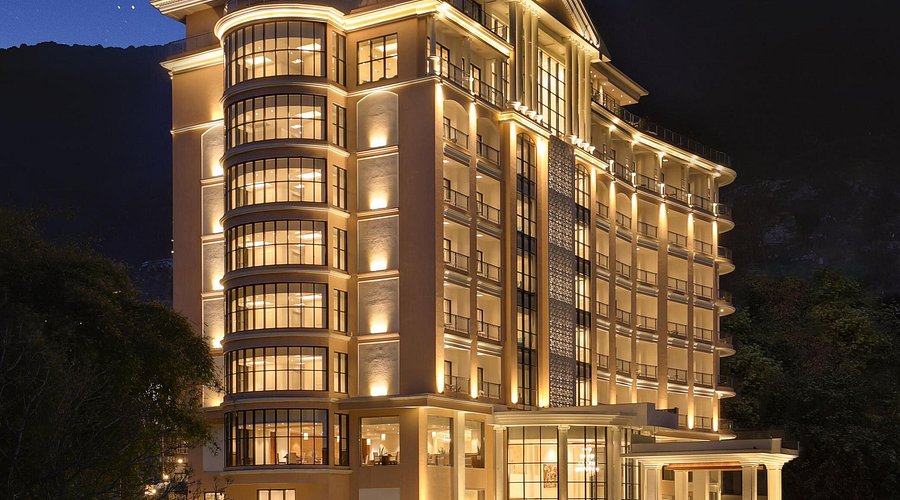
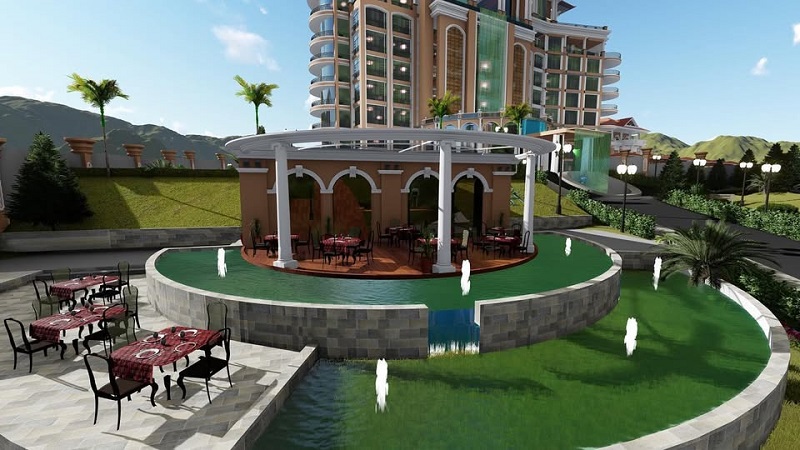
Budhanilakantha Heritage Limited (BHL), which operates a five-star hotel in Budhanilakantha, Kathmandu, under the ‘Lemon Tree Premier’ brand, has received a reaffirmation of its [ICRANP-IR] B+ issuer rating from ICRA Nepal. The company operates a 99-key hotel, expandable to 102 keys, and has been established as a special-purpose vehicle (SPV) for the hospitality project. The hotel operates under a 20-year franchise agreement with Lemon Tree Hotels Limited (LTHL), an established hotel chain with more than 100 properties across India, Bhutan, Nepal, and Dubai. BHL’s hotel commenced partial operations on March 9, 2024, and became fully operational from mid-September 2024. The company has also applied to the Securities Board of Nepal (SEBON) for an initial public offering (IPO) of NPR 495 million.
ICRA Reaffirms ‘B+’ Issuer Rating
ICRA Nepal has reaffirmed Budhanilakantha Heritage Limited (BHL)’s issuer rating at [ICRANP-IR] B+, pronounced “ICRA NP Issuer Rating B Plus.” According to ICRA Nepal, issuers carrying this rating are considered to have a high risk of default regarding the timely servicing of financial obligations. The issuer rating reflects an opinion on the general creditworthiness of the entity and is not specific to any individual debt instrument. The reaffirmation comes despite continued pressure on the company’s debt servicing capacity, liquidity and return indicators. ICRA Nepal said Budhanilakantha Heritage Limited (BHL)’s financial profile remains constrained by a weak debt service coverage ratio (DSCR), high debt relative to operating profit and a stretched liquidity position.
Revenue and Occupancy Show Improvement
Budhanilakantha Heritage Limited (BHL) recorded a modest improvement in its core operating performance during FY2026, with revenue increasing by around 4%. The hotel’s occupancy rate improved significantly to approximately 49% in FY2026, compared with around 36% in FY2025. The improvement came despite disruptions to Nepal’s tourism industry following the September 2025 riots. The increase in occupancy helped raise the hotel’s revenue per available room (RevPAR) by around 21% during FY2026 compared with the previous rating assessment. However, the company had to reduce its average daily room rate (ADR) by around 11% amid competitive pressure, limiting the overall benefit from higher occupancy.
Operating Profit Margin Turns Positive
The company’s operating profitability improved substantially during FY2026. Budhanilakantha Heritage Limited (BHL)’s operating profit margin (OPM) increased to around 30%, compared with a negative OPM of approximately 3% in FY2025. ICRA Nepal attributed the improvement to higher occupancy, increased RevPAR, controlled operating expenses and the addition of a new revenue stream. The company entered into a rental agreement with a casino, with rental income commencing in December 2025. At the same time, its operating costs declined by around 28% during FY2026, supporting the improvement in operating profitability. Despite this progress, the company continued to report a negative net profit margin of around 3.2%, mainly due to high finance and depreciation costs.
Debt Coverage Remains Under Pressure
Despite improvements in operating performance and lower debt levels, Budhanilakantha Heritage Limited (BHL)’s debt coverage indicators remain weak. The company’s DSCR stood at around 0.5 times in FY2026, indicating that operating cash generation remained insufficient to comfortably cover its debt servicing obligations. Similarly, its total debt to operating profit before interest, tax, depreciation and amortisation (TD/OPBITDA) stood at approximately 10 times as of mid-July 2026. ICRA Nepal noted that the company benefited from a relatively favourable borrowing-rate environment and reduced its overall debt during FY2026. However, the agency said the ability to sustainably improve debt coverage and operating profitability will remain an important monitorable.
Gearing Falls Following Rights Issue
Budhanilakantha Heritage Limited (BHL)’s capitalisation profile improved during FY2026 following a reduction in debt. The company’s gearing declined to approximately 0.5 times as of mid-July 2026, compared with around 1.3 times in mid-July 2025. The reduction was supported by proceeds from a rights issue, through which the company prepaid approximately 36% of its term debt during the third quarter of FY2026. However, ICRA Nepal noted that the company’s operating cash flows have not yet been sufficient to independently support its debt repayments and other funding requirements. Shortfalls have therefore been supported by the proceeds from the rights issue.
Liquidity Position Remains Stretched
Liquidity continues to be a major concern for Budhanilakantha Heritage Limited (BHL), according to ICRA Nepal. The company’s operating cash flows remain insufficient to fully support debt repayments, while capital expenditure requirements for upgrading and maintaining hotel amenities have added to its funding needs. The company’s working capital loan limits have also been fully utilised since FY2025, leaving limited immediate borrowing headroom in the event of unexpected funding requirements.
Budhanilakantha Heritage Limited (BHL)’s net working capital intensity stood at approximately 76% of operating income as of mid-July 2026, slightly higher than around 73% a year earlier. ICRA Nepal said the company’s ability to control working capital intensity and generate adequate cash flows to meet operational, financial and other expenditure requirements will remain a key monitorable.
Return Indicators Remain Weak
Budhanilakantha Heritage Limited (BHL)’s return indicators remained under pressure during FY2026, although they improved from the previous year. The company continued to carry accumulated losses equivalent to around 14% of its paid-up capital as of mid-July 2026. The increase in paid-up capital following the rights issue has also affected return metrics. During FY2026, the company’s return on net worth (RoNW) was around 0.6%, while return on capital employed (RoCE) stood at approximately 1.9%. Its net profit margin remained negative at around 3.2%. However, the NPM improved significantly from approximately negative 88% in FY2025, which had been the major contributor to the company’s accumulated losses.
Lemon Tree Affiliation Supports Hotel’s Market Position
ICRA Nepal continues to draw comfort from Budhanilakantha Heritage Limited (BHL)’s affiliation with Lemon Tree Hotels Limited through its 20-year franchise agreement. The use of the Lemon Tree Premier brand provides BHL with greater visibility, access to the franchisor’s reservation system and its established customer base.
According to ICRA Nepal, the affiliation contributed to the hotel’s ability to achieve around 49% occupancy in FY2026 despite disruptions affecting Nepal’s tourism sector. The company has also maintained an active focus on the MICE (Meetings, Incentives, Conferences and Exhibitions) segment, which has supported its operating performance.
Limited Operating Track Record Remains a Concern
The hotel remains relatively new, having commenced partial operations in March 2024 and reaching full operations only from mid-September 2024. As a result, FY2026 represented the company’s first full year of operations. ICRA Nepal noted that the hotel’s organic business momentum could not be fully assessed during the year because the tourism industry experienced significant operational disruptions following the September 2025 riots.
Although the hotel property itself was not directly affected by the riots, the broader impact on tourism and foreign visitor arrivals affected the operating environment. Budhanilakantha Heritage Limited (BHL)’s limited operating track record and the need to establish stable performance therefore remain key monitorable factors.
Tourism Sector Exposure Adds External Risks
Like other hospitality companies, Budhanilakantha Heritage Limited (BHL) remains exposed to the cyclical and seasonal nature of the tourism industry. Its revenue could be affected by macroeconomic conditions, geopolitical developments, terrorist incidents, disease outbreaks, and other external shocks that influence tourist arrivals and travel demand. Budhanilakantha Heritage Limited (BHL) also faces competition from both established and newly developed hotels in Kathmandu and surrounding areas, which could put pressure on room rates and occupancy.
Sustained Improvement Could Support Future Rating
ICRA Nepal said a sustained scale-up in revenue and profitability, together with improvements in debt coverage indicators and liquidity, could support a positive rating action in the future. Conversely, weakening operating metrics leading to sustained pressure on revenue and profitability could further deteriorate debt coverage and liquidity, creating downward pressure on the rating.
ICRA Nepal also expects promoter support to cover any debt servicing shortfalls over the medium term. Any delay or shortfall in such support could exert additional downward pressure on the rating. Going forward, the company’s ability to improve occupancy, RevPAR, profitability, debt coverage and liquidity, as well as manage interest-rate volatility, will remain crucial to its financial performance and credit profile.