ICRA Nepal has reaffirmed the issuer rating of Hotel Ichchha Limited (HIL) at [ICRANP-IR] BB, citing expected improvement in the hotel’s business profile following its affiliation with Lemon Tree Hotels Limited, improved RevPAR and significantly reduced leverage.
Lemon Tree affiliation to strengthen business profile
ICRA Nepal said the rating reaffirmation primarily reflects the expected improvement in Hotel Ichchha Limited (HIL)’s operational and business profile following its affiliation with Lemon Tree Hotels Limited (LTHL) from April 2, 2026. Under the 20-year license agreement, the hotel is operating under the ‘Lemon Tree Premier’ brand, an upper mid-scale five-star category brand of LTHL. The affiliation is expected to improve Hotel Ichchha Limited (HIL)’s market visibility and provide access to Lemon Tree’s reservation network, loyalty programmes and broader customer base. LTHL operates more than 100 hotels across India, Sri Lanka and Nepal, providing Hotel Ichchha Limited (HIL) with additional brand and customer access.
RevPAR rises by around 30%
The hotel recorded a significant improvement in revenue per available room (RevPAR) during FY2026. RevPAR increased to NPR 2,392 in FY2026 from NPR 1,842 in FY2025, representing an increase of around 30%. The improvement was supported by occupancy of around 53% in FY2026, compared with approximately 48% in FY2025 and 29% in FY2024. However, the hotel operated only 69 rooms out of its total 97 keys during FY2026 due to ongoing renovation and upgrading works.
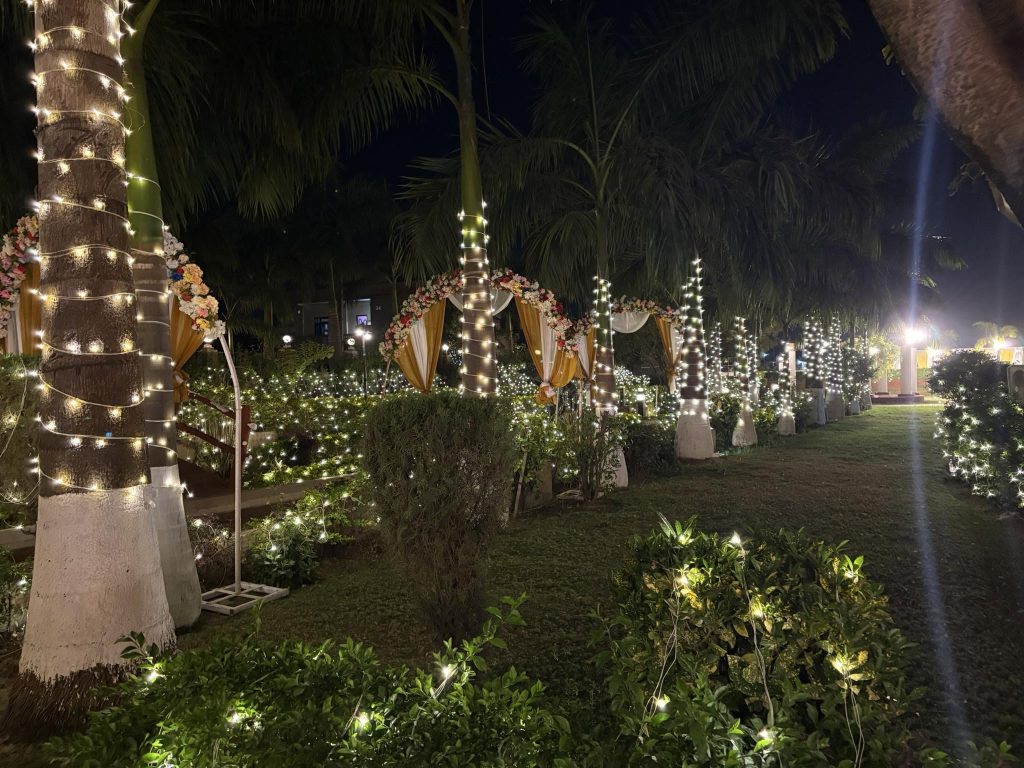
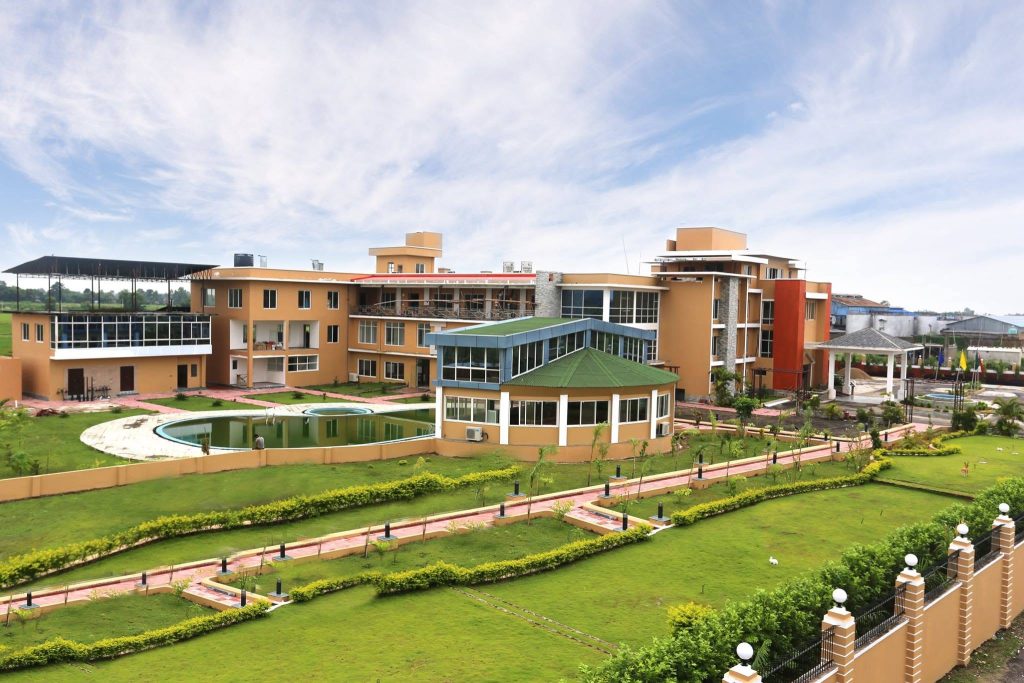
ICRA Nepal noted that Hotel Ichchha Limited (HIL) has been able to command some premium in room tariffs due to its strategic location in Simara, Bara, an industrial town close to the Indo-Nepal border. The property is also currently the only five-star category hotel in the region, providing it with a first-mover advantage.
Equity infusion improves leverage
The rating agency also highlighted Hotel Ichchha Limited (HIL)’s improved capital structure, supported by substantial equity infusion for ongoing renovations and infrastructure development. The company invested around NPR 231 million in FY2026, following capital expenditure of approximately NPR 595 million in FY2025, with the investments primarily funded through equity. As a result, Hotel Ichchha Limited (HIL)’s paid-up capital increased to approximately NPR 1.40 billion as of mid-July 2026, compared with NPR 975 million a year earlier and NPR 405 million as of mid-July 2024.
The company’s total debt-to-tangible net worth (TD/TNW) ratio consequently declined to 0.3 times in FY2026 from 1.2 times in FY2024, indicating a substantial improvement in leverage. Hotel Ichchha Limited (HIL) is also planning to raise NPR 350 million through an initial public offering (IPO). The proceeds are planned to be utilised for the repayment of its project loan, which stood at around NPR 376 million as of mid-July 2026.
Revenue declines amid renovation-related capacity constraints
Despite improvements in RevPAR and occupancy, Hotel Ichchha Limited (HIL)’s overall revenue base remained modest due to the reduced number of operational rooms. The company’s operating income declined to NPR 142 million in FY2026 from NPR 173 million in FY2025. Similarly, its operating profit margin (OPM), measured by OPBDITA/OI, declined to 45% from 57% over the same period.
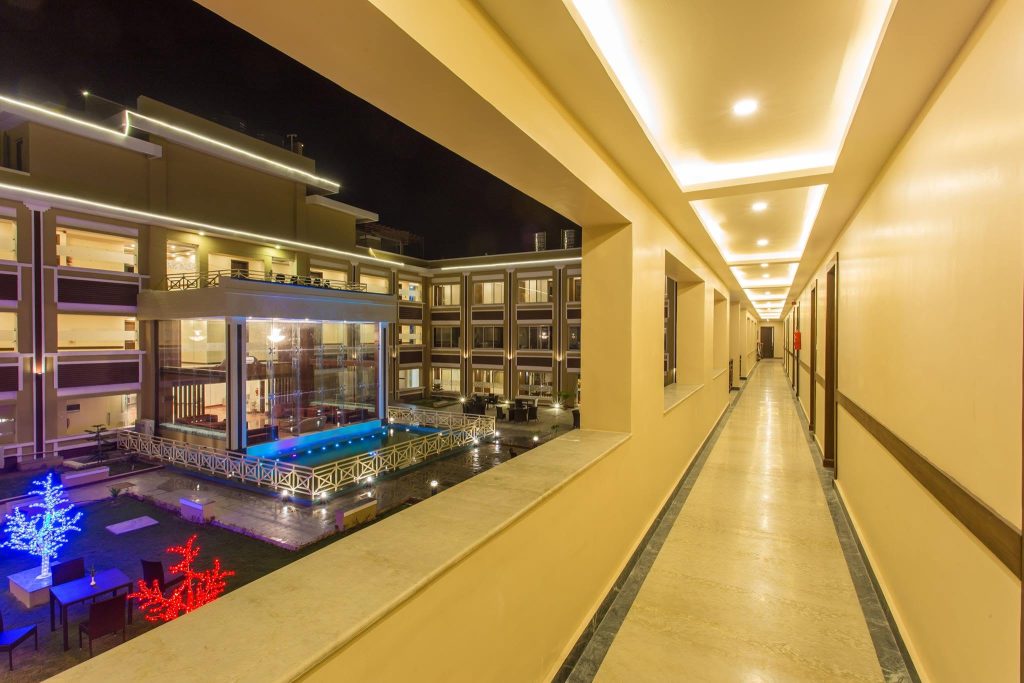
ICRA Nepal attributed the pressure partly to the ongoing renovation and upgrading activities, which restricted the hotel’s operational capacity. The company’s return on capital employed (RoCE) also declined to around 3% in FY2026 from 8% in FY2025, reflecting the impact of the expanded equity base and the temporarily constrained operating profile.
High working capital intensity remains a concern
ICRA Nepal has flagged Hotel Ichchha Limited (HIL)’s high working capital intensity and liquidity position as key rating constraints. The company’s net working capital-to-operating income ratio stood at around 111% as of mid-July 2026, although it had improved from approximately 208% in the nine months of FY2025.
The high working capital requirement was largely attributed to elevated inventory levels. Inventory of food and beverages, guest supplies, fuel and gas, linen and other items stood at around NPR 19 million out of total inventory of approximately NPR 24 million. Ongoing renovation-related capital expenditure, together with the high operating leverage inherent in the hotel business, could continue to place pressure on the company’s cash flows and liquidity.
Government support and promoter strength provide comfort
The rating also takes comfort from the Government of Nepal’s initiatives to support the tourism industry. These include minimum lending requirements for tourism-related projects, interest capitalisation during construction, the Visit Nepal Decade 2023–2033 initiative and other measures aimed at strengthening tourism demand. ICRA Nepal also noted the promoter group’s presence across multiple sectors, including hospitality, education and real estate, which provides additional support to the company’s growth prospects.
Limited operating track record remains a rating constraint
Despite the positive developments, Hotel Ichchha Limited (HIL) continues to have a relatively limited operating track record. The hotel has operated as a four-star property since 2017 and received its five-star license only in March 2023. Its operations also remain concentrated in a single property, limiting geographical and business diversification. ICRA Nepal said the company’s performance will remain dependent on its ability to complete the ongoing renovation on time, restore operations to full capacity, improve revenue and margins, and capture the benefits of its Lemon Tree affiliation. The fragmented and cyclical nature of the hotel industry, competition from existing and upcoming properties, pricing pressure, macroeconomic conditions and interest-rate volatility also remain key risks.
IPO and deleveraging to remain key rating sensitivities
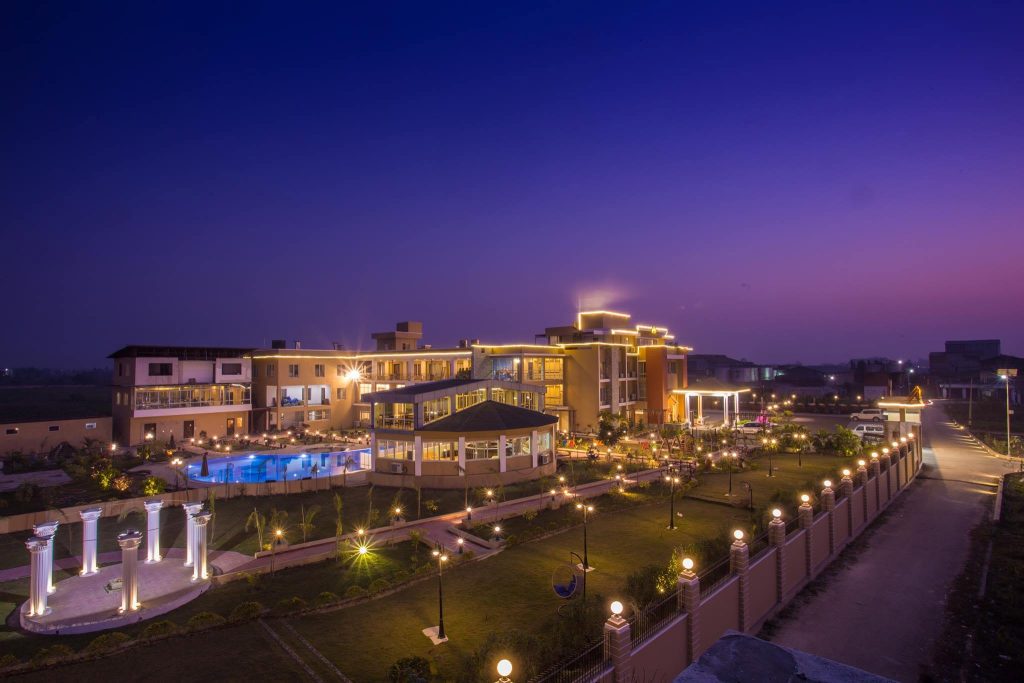
Going forward, ICRA Nepal will closely monitor Hotel Ichchha Limited (HIL)’s ability to improve revenue and margins, manage working capital intensity, complete its planned IPO on time and utilise the proceeds for debt reduction. The rating could be upgraded if the company operates at full capacity, scales up revenue, improves margins and coverage indicators, completes the proposed IPO in a timely manner and uses the proceeds for deleveraging. Conversely, further deterioration in margins, coverage indicators, working capital intensity or liquidity could exert downward pressure on the rating.
Financial performance
Hotel Ichchha Limited (HIL)’s operating income increased from NPR 60 million in FY2022 to NPR 173 million in FY2025, before declining to NPR 142 million in FY2026. Its OPBDITA/OI improved substantially from 9% in FY2022 to 74% in FY2024, before moderating to 57% in FY2025 and 45% in FY2026. Total debt-to-tangible net worth declined sharply from 6.0 times in FY2022 to 0.3 times in FY2026, while total outside liabilities-to-TNW fell from 6.8 times to 0.4 times during the same period.
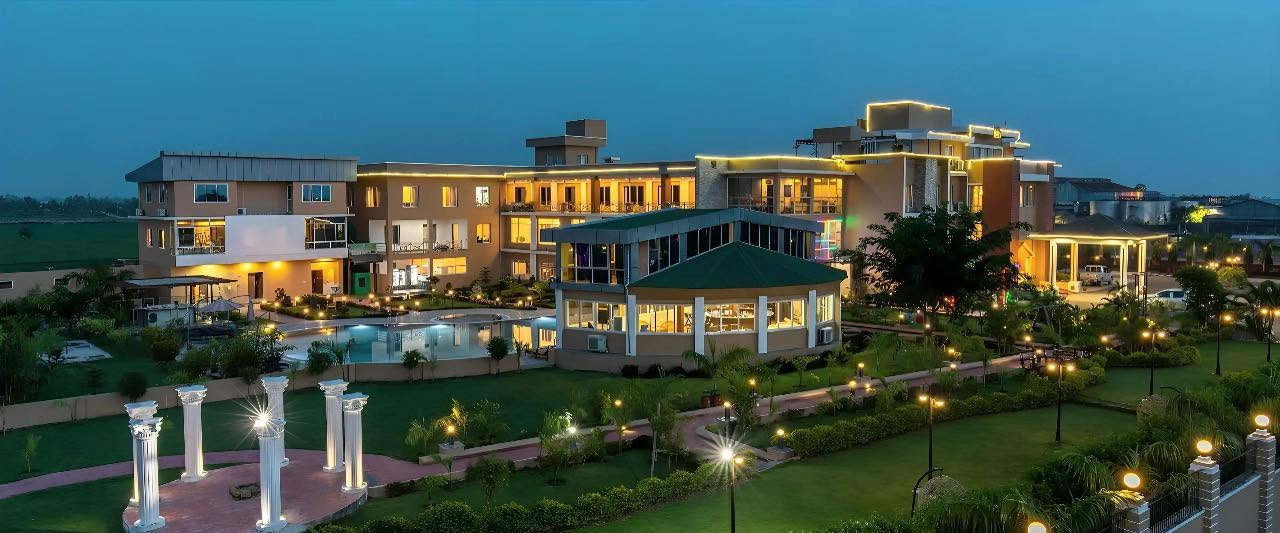
Interest coverage improved to 4.0 times in FY2026, while DSCR stood at 1.2 times. The current ratio also improved significantly to 4.7 times from 1.7 times in FY2025. Hotel Ichchha Limited was incorporated as a private limited company in September 2015 and converted into a public limited company on June 3, 2024. The company operates a 97-key five-star hotel in Simara, Bara, under the Lemon Tree Premier brand. The company is promoted by Ichchha Bahadur Wagle and his family members and associates.